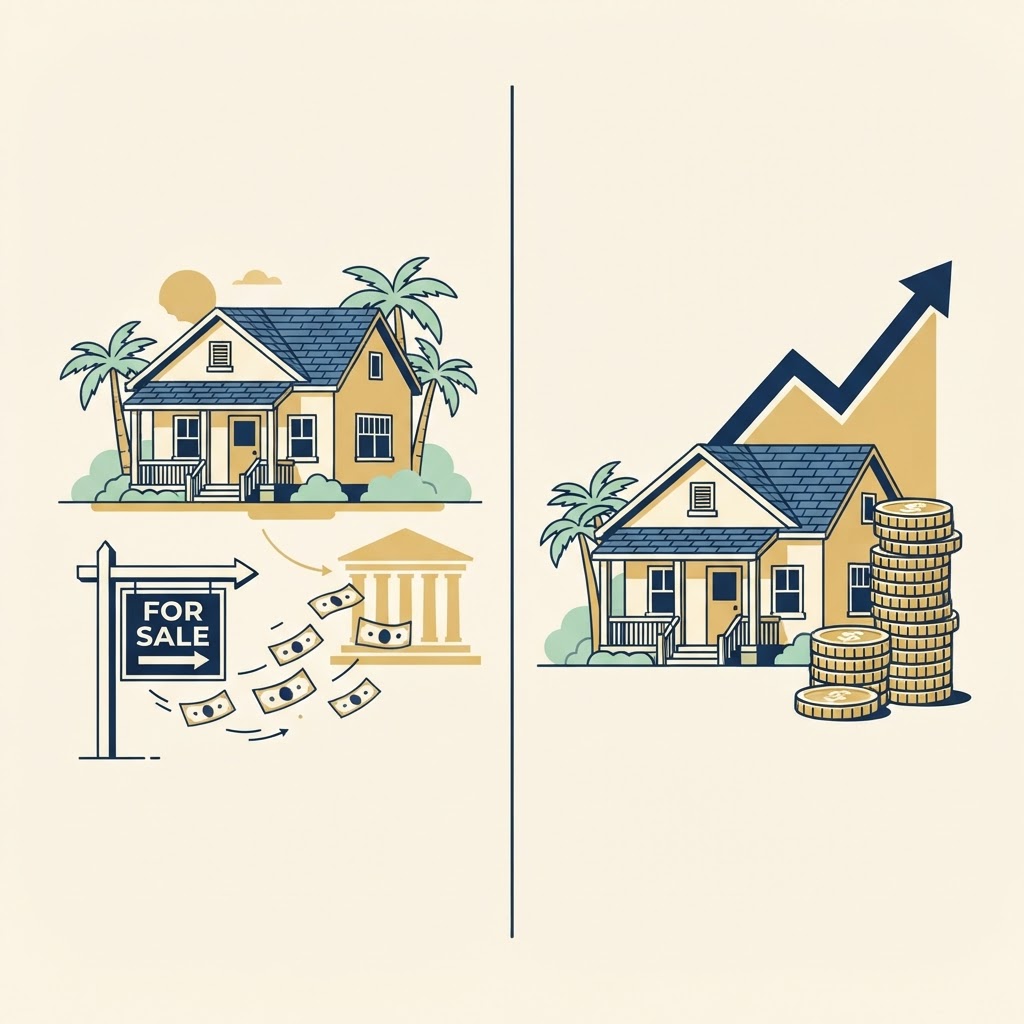
Selling your rental property might seem like the big payday you envisioned when you first purchased it. But there is a lot more to selling than just finding a buyer. It's expensive!
You already know about real estate commissions, documentary stamps, title insurance, and legal fees, but do you realize how much the IRS is going to take?
Depending on how long you've owned the property, federal taxes — including capital gains, recaptured depreciation, and possibly Net Investment Tax — can be a real gut punch! Many investors regret selling once they see the tax bill.
Many experienced real estate investors consider refinancing before deciding to sell. Instead, they leverage the property's equity to access tax-free cash via cash-out refinance or HELOC, all while retaining ownership, earning continued rental income, and future appreciation.
Then, if they want to offload their landlord duties, they hire a property management company and enjoy their passive income.
Below, I've laid out the elements that make up these transactions. Finally, here is a link (Click Here) to a YouTube video by tax attorney Toby Mathis titled: 'Buy, Borrow, Die.' It's a terrible title, but the strategy is simple: acquire appreciating assets, borrow against the equity rather than sell, and eventually pass the property to heirs with a stepped-up basis.
Read on for more details.
Selling Rental Property — The Costs
Real Estate Agent Fees
If you use a real estate agent to sell, the commission is typically 3% to 6% of the selling price.
Closing Costs
Including title insurance, legal fees, escrow fees, transfer taxes, and so on.
Capital Gains Tax
If the selling price exceeds the original purchase price, you'll owe between 15% and 20% (depending on your tax bracket) in capital gains tax on the difference.
Depreciation Recapture
Each year, IRS permits residential rental property to be depreciated over 27.5 years. When the property is sold, the accumulated depreciation is generally subject to depreciation recapture tax at rates of up to 25%.
Net Investment Income Tax (NIIT)
If your modified adjusted gross income exceeds the applicable threshold, you may owe an additional 3.8% Net Investment Income Tax on some or all of the gain from the sale.
Other Potential Costs
Like repairs needed to sell the property, and mortgage payoff, etc.
Refinance & Hold (See Example Below)
Tax-Free Cash
By refinancing, you put the proceeds of the loan in your pocket, which are not taxable.
Continued Ownership
You maintain ownership of the property and collect rent just like before.
Historically, inflation and Florida's population growth have contributed to rising rents and increasing property values.
As rents increase over time, property values often increase as well, potentially creating opportunities for future refinancing or additional equity growth.
Management
If you want to end your landlord responsibilities, hire a property management company to assume those demands. For many owners, professional management is well worth the cost.
Rental Income Can Pay Debt Service
In many cases, rental income can substantially offset or fully cover the new debt service, although results vary based on financing terms, rents, taxes, insurance, and operating expenses.
Stepped-Up Basis at Death
Upon your passing, the property's tax basis is "stepped up" to its current market value. This means your heirs inherit the property at its new, higher basis — which means, if they want, they can immediately sell and potentially avoid capital gains and depreciation recapture taxes that would otherwise have been due during your lifetime.